
Most small businesses pay far less for cyber insurance than they expect, but the range is wide. Your headcount, industry, and security controls move the price more than anything else.
Quick answer: A small business with 1–4 employees pays about $83 a month for cyber insurance, based on MoneyGeek’s September 2026 benchmark (modeled, $1M limit). Sample industries run from $52 to $157 a month, and Insureon reports an average near $129 a month with policies starting around $35. Your own quote depends on size, industry, limits, and security controls.
Key takeaways
- Benchmark: about $83/month for 1–4 employees (MoneyGeek, 2026).
- Industry matters: tech/IT sits near the top of the sampled range at $157/month; agriculture near the bottom at $52 (MoneyGeek, 2026).
- Size matters: premiums rise as headcount grows; see the size table below.
- Controls can lower the price or decide if you are offered a policy at all. See cyber insurance requirements.
- Modeled prices are not quotes. Treat every figure here as a starting range.
On this page: Benchmark · By industry · By size · Price factors · Why quotes differ · Lower your cost · Is it worth it? · Prepare for a quote · FAQ
What is the average cost of cyber insurance for a small business?
The national benchmark is about $83 per month (roughly $996 a year) for a business with 1–4 employees, according to MoneyGeek’s report updated September 10, 2026. MoneyGeek’s modeled premiums span $52 to $3,398 a month depending on the business profile.
Different sources report different averages because they measure different customers:
| Source | Figure | What it measures |
|---|---|---|
| MoneyGeek (Sept 2026) | ~$83/month benchmark | Modeled premium, 1–4 employees, $1M limit |
| MoneyGeek (Sept 2026) | $52–$3,398/month | Range across modeled business profiles |
| Insureon | ~$129/month average; from ~$35 | Prices from its own small-business customers |
Use the benchmark as an anchor, not a promise. A modeled premium assumes a standard profile. An actual quote reflects your answers about security.
Cyber insurance cost by industry
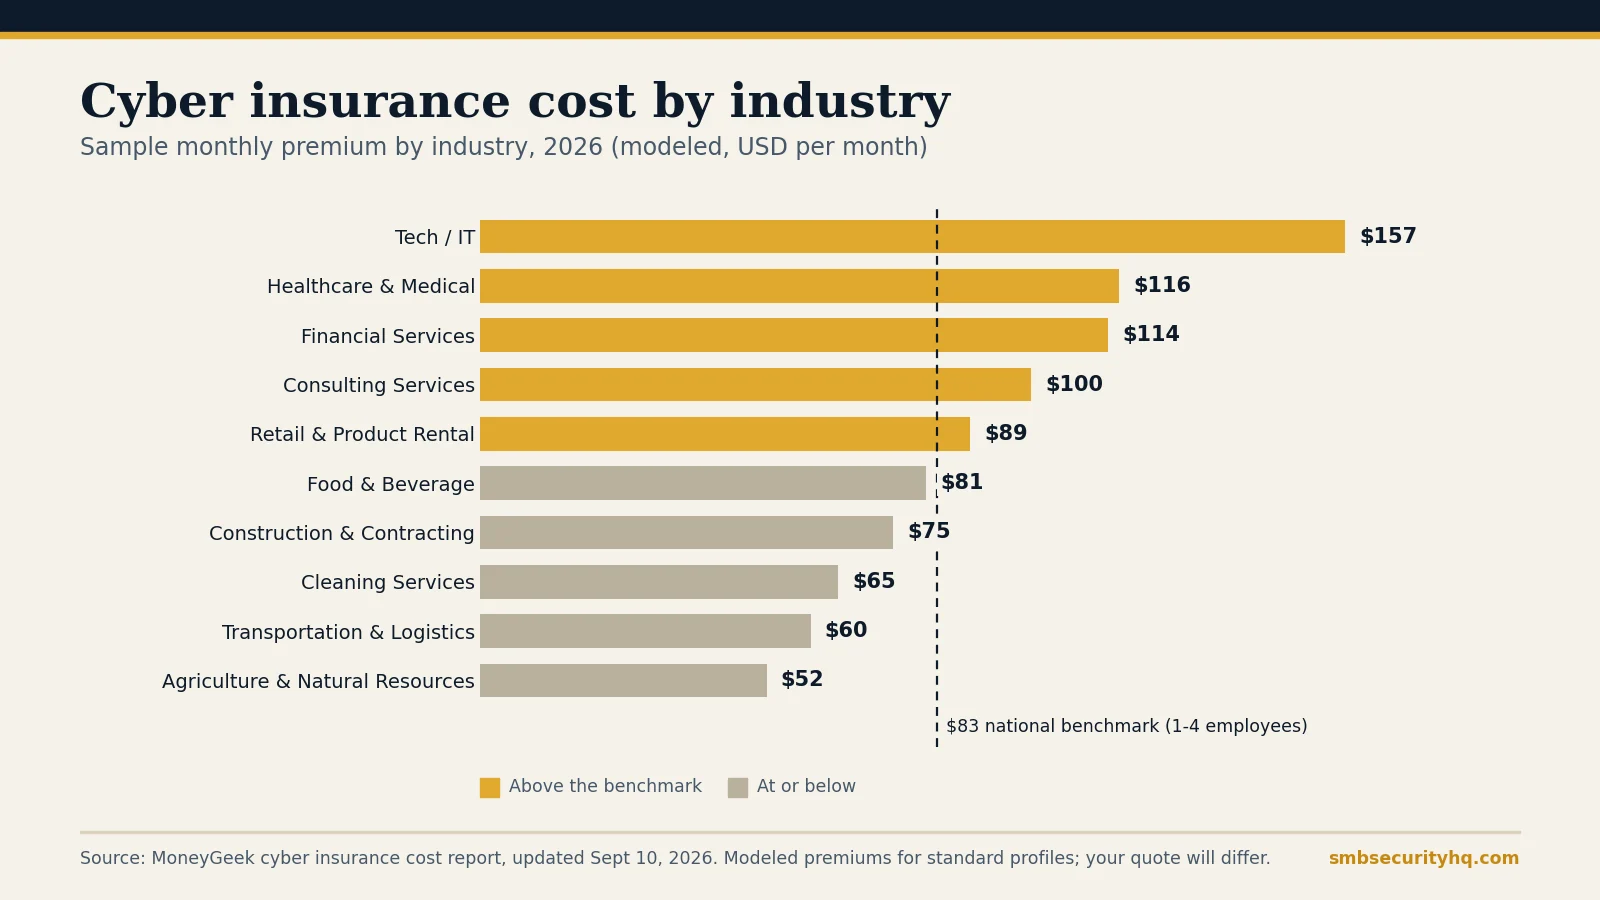
Industry changes the price because insurers see different amounts of sensitive data and different loss patterns. MoneyGeek’s sample premiums for 2026:
| Industry | Sample monthly premium |
|---|---|
| Tech / IT | $157 |
| Healthcare & medical | $116 |
| Financial services | $114 |
| Consulting services | $100 |
| Retail & product rental | $89 |
| Food & beverage | $81 |
| Construction & contracting | $75 |
| Cleaning services | $65 |
| Transportation & logistics | $60 |
| Agriculture & natural resources | $52 |
Source: MoneyGeek, updated September 10, 2026. Modeled premiums for standard profiles.
Read the table this way: if you handle client data, health records, or payments, expect to land above the benchmark. If you hold little sensitive data, you may land below it.
How company size affects cyber insurance cost
More employees means more accounts, devices, and chances for a mistake, so premiums climb with headcount. MoneyGeek reports these relative differences:
| Company size | Difference in premium (MoneyGeek, 2026) |
|---|---|
| 1–4 employees | Baseline (about $83/month) |
| 5–9 employees | About 45% higher than 1–4 employees |
| 20–49 employees | About 325% higher than a sole proprietor |
The percentages are relative comparisons, not dollar quotes. Multiply them against a realistic starting number for your industry, then ask an agent to confirm.
What factors change the cost of cyber insurance?
Six inputs do most of the work.
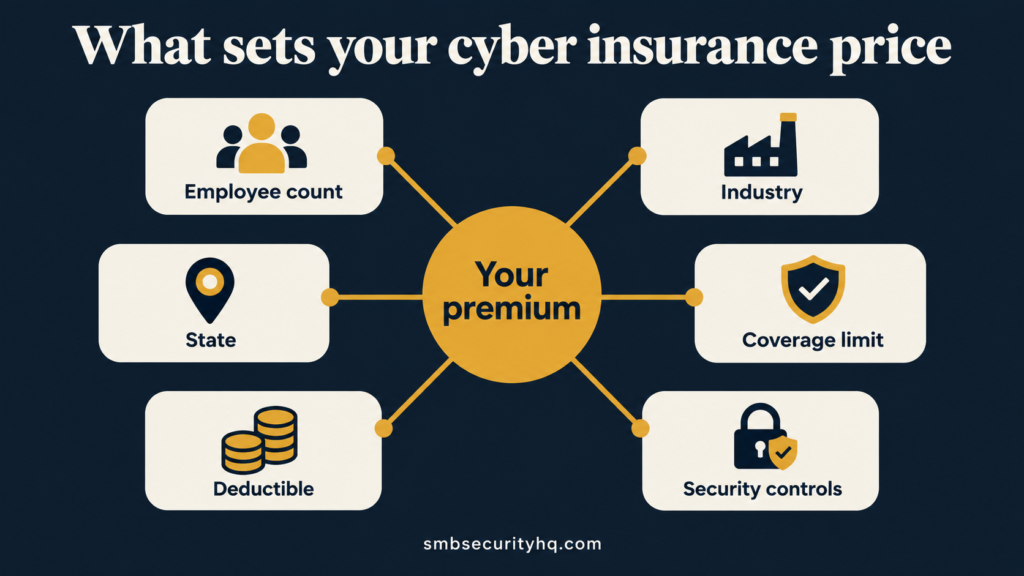
- Number of employees. More staff, more exposure.
- Industry. Data-heavy and regulated fields cost more (see the table above).
- State. Location affects both claims patterns and regulation.
- Coverage limit. A $2M limit costs more than a $1M limit.
- Deductible. A higher deductible lowers the premium but raises what you pay after an incident.
- Security controls. MFA, tested backups, and endpoint protection can improve your terms or decide whether you are offered coverage.
MoneyGeek ranks these inputs by influence on its modeled premiums. Treat the ranking as directional; your insurer’s own model will weigh them differently.
Why do cyber insurance quotes differ so much?
Three reasons explain most gaps between two quotes for the “same” business:
- Modeled vs. actual customers. A benchmark uses a standard profile. A real quote uses your application.
- Different limits and exclusions. A cheaper policy may exclude social engineering or cap ransomware payouts. Compare coverage, not just price. The pillar guide lists common exclusions.
- Different insurer appetite. Some carriers want your industry; others avoid it.
If one quote looks far cheaper, read its exclusions and sub-limits before you celebrate.
How can you lower your cyber insurance premium?
You cannot negotiate with an algorithm, but you can change its inputs.
- Enforce MFA on email, remote access, admin accounts, and finance tools. Partial MFA is still a gap.
- Deploy endpoint detection and response (EDR) on every computer.
- Keep encrypted backups with one isolated copy, and test restores.
- Document patching and staff training. Insurers want evidence.
- Shop at least three quotes with identical limits and deductibles.
- Consider a higher deductible only if your business can absorb it.
Do not shortcut the application. Answering a security question inaccurately can put a later claim at risk. The requirements guide explains what to keep as proof.
Is cyber insurance worth the cost?
Compare the premium with the loss. Coalition’s 2026 Cyber Claims Report puts the average claim loss across its policyholders at $116,000 in 2025, with ransomware claims averaging $269,000 and funds transfer fraud $141,000.
A premium near $999 a year is under 1% of a $116,000 loss. That arithmetic is illustrative, not a forecast: most businesses never file a claim, and your own loss could be far smaller or larger. The useful question is whether you could pay a five- or six-figure bill from cash without closing a door.
If you could not, a cyber policy is a reasonable way to transfer that risk. If your business holds very little data and has no money-movement exposure, you may reasonably choose a lower limit.
How to prepare for an accurate quote
Have these ready before you ask for quotes:
- Annual revenue and number of employees
- Industry and what sensitive data you store (customer records, payment data, health data)
- Where your data lives (cloud services, local servers)
- Whether MFA is enforced on email, remote access, admin and finance tools
- Which backup system you use and when you last tested a restore
- Your endpoint protection product
- Any past incidents or claims
- Desired limit and deductible
Want to know your likely readiness first? Use our free Cyber Insurance Readiness Check. To compare quotes from licensed partners, use our quote partner. This is a referral link and we may earn a commission at no cost to you; see our Affiliate Disclosure.
Frequently asked questions
How much does cyber insurance cost for a small business per month?
About $83 a month is the 2026 benchmark for a business with 1–4 employees (MoneyGeek, modeled, $1M limit). Sample industries range from $52 to $157 a month, and Insureon reports an average near $129 with policies from about $35.
How much does cyber insurance cost per year?
The $83 monthly benchmark works out to roughly $996 a year. Your actual premium depends on size, industry, limits, deductible, state, and security controls.
What is the cheapest cyber insurance for a small business?
The cheapest policy is rarely the best value. Low prices often come with lower limits or exclusions for social engineering or ransomware. Compare identical limits and read exclusions before choosing on price.
Does company size change the price?
Yes. MoneyGeek’s data shows premiums about 45% higher for 5–9 employees than for 1–4, and about 325% higher for 20–49 employees than for a sole proprietor.
Which industries pay the most?
In MoneyGeek’s 2026 sample, tech/IT ($157/month), healthcare ($116) and financial services ($114) sit highest. Agriculture ($52) and transportation ($60) sit lowest.
Can I lower my cyber insurance cost?
Often, yes. Enforced MFA, EDR, tested backups, and documented training improve the profile insurers see. Compare at least three quotes with the same limits.
Is cyber insurance tax deductible?
Business insurance premiums are often deductible as a business expense, but rules vary. Ask your accountant.
Sources
- MoneyGeek: Cyber insurance cost (updated Sept 10, 2026)
- Insureon: Cyber insurance cost
- Coalition: 2026 Cyber Claims Report (published Mar 5, 2026)
- Cyber Readiness Institute: Cyber insurance FAQs
Last updated October 1, 2026. Prices are modeled benchmarks and change; confirm with a licensed agent. SMB Security HQ provides general information, not insurance, legal, or financial advice. See our Affiliate Disclosure and How We Test.
Written by SMBSecurity Team, Sunteco Security Team. Reviewed by Nhon Dang, CTO.